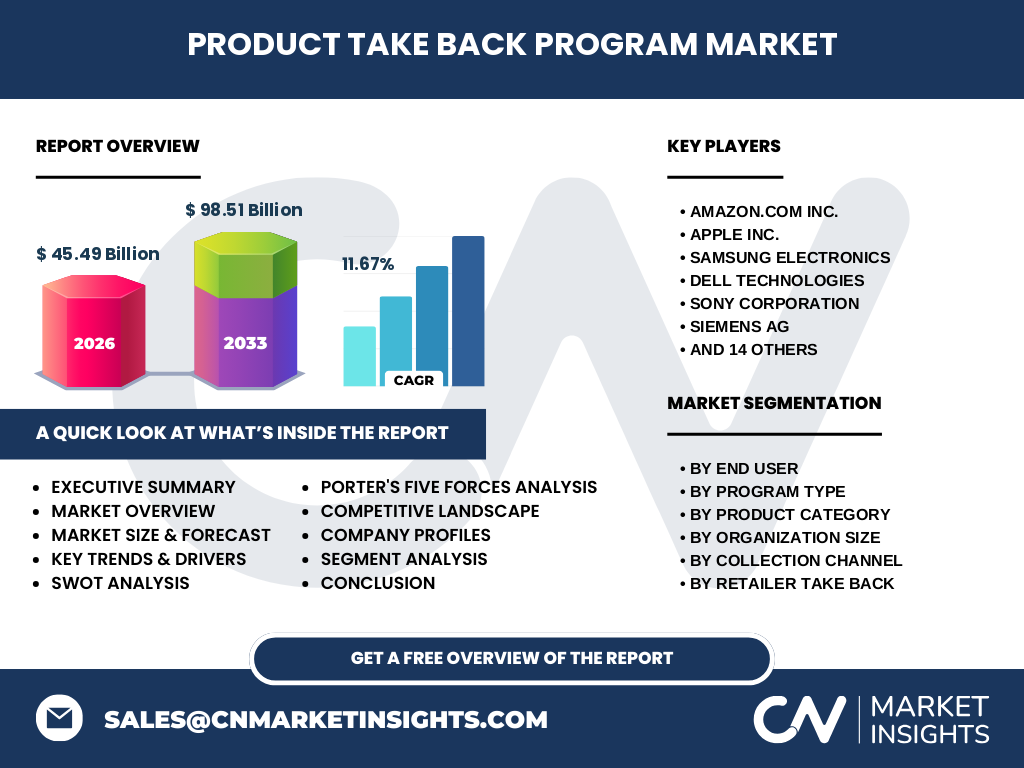
Market overview of the Product Take-Back Program Market
Our analysis indicates that the Product Take-Back Program Market is valued at 45.49 Billion in 2026. This sector covers structured collection, reverse logistics, and end-of-life processing for consumer and industrial goods, driven by strict regulatory mandates like the EU WEEE Directive and corporate ESG commitments.
Key market drivers, restraints, challenges, and opportunities shaping Product Take-Back Program Market
The market is propelled by tightening environmental regulations regarding rare earth metals and e-waste. However, high reverse logistics costs and complex supply chain fragmentation act as major restraints. Opportunities lie in automated sorting hubs managed by Waste Management Contractors and Reverse Logistics Providers.
Structural Growth Trends in Product Take-Back Program Market
Based on our research, the shift toward circular economy frameworks has accelerated adoption. Companies are leveraging Direct Return Programs and incentive-based collection models to secure critical secondary raw materials, reducing virgin material dependency amidst raw material price volatility.
COVID-19 impact analysis and recovery trajectory
The pandemic initially disrupted physical collection channels like in-store drop-offs and retail take-backs. However, it catalyzed a surge in digital mail-back programs and online trade-ins, leading to a resilient recovery trajectory spearheaded by major e-commerce platforms.
Competitive Benchmarking and Market Dynamics
The competitive landscape features dominant technology leaders such as Apple Inc., Samsung Electronics, and Amazon.com Inc. Market concentration is high among top-tier enterprises deploying sophisticated device trade-in platforms, while specialized players handle industrial remanufacturing.
Executive summary of key findings for Product Take-Back Program Market
Our executive analysis projects the Product Take-Back Program Market to surge from 45.49 Billion in 2026 to 98.51 Billion by 2033, expanding at a robust 11.67% CAGR. Success requires integrated omnichannel collection channels across residential and commercial sectors.
Long-term market forecast from 2027 to 2033
The data suggests sustained acceleration, forecasting market expansion up to 98.51 Billion by 2033. This trajectory is fueled by mandatory producer responsibility laws in electronics, automotive, and packaging verticals across key global economies.
Segmentation analysis across product categories and end users
Segmentation spans end-users (Residential, Commercial, Industrial), program types (Retailer, Manufacturer, Third Party), and product categories (Electronics, Appliances, Packaging, Textiles, Automotive). Electronics and Appliances dominate volume, leveraging drop-off centers and in-store collection channels.
Regional market analysis and geographic distribution
Geographic performance is heavily skewed toward regions with stringent environmental legislation. North America and Europe lead adoption, driven by established regulatory frameworks, whereas Asia-Pacific exhibits the fastest growth due to expanding urban e-waste generation.
In-depth regional review of high-growth territories
European markets benefit from rigorous statutory take-back obligations enforced by national agencies. Meanwhile, North American growth is led by proactive corporate initiatives from enterprises like Dell Technologies and Best Buy Co. Inc. optimizing reverse supply chains.
Company profiles and strategic positioning of leading participants
Industry giants like Hewlett Packard Enterprise (HPE) and Cisco Systems anchor enterprise IT asset disposition. Consumer-facing firms like Sony Corporation and LG Electronics integrate take-backs directly into retail and warranty return architectures.
Porter's Five Forces analysis of the industry
Bargaining power of suppliers is moderate due to specialized reverse logistics dependencies. Threat of substitutes is low given strict disposal bans. Competitive rivalry is intense, compelling firms like Xerox Corporation and Canon Inc. to innovate in remanufacturing.
SWOT analysis of the Product Take-Back Program Market
Strengths include established retail footprints and brand loyalty. Weaknesses involve high reverse shipping expenses. Opportunities reside in AI-driven sorting technologies, while threats stem from complex cross-border regulatory compliance governing hazardous e-waste transport.
Value chain analysis from raw materials to end-users
The value flow initiates with original equipment manufacturers and flows through collection channels—such as mail back and drop off centers—to Recycling Service Providers who extract commodities for reintegration into manufacturing supply chains.
Investment insights and strategic high-potential areas
Investors should target Collection Hub Services and automated grading platforms. Companies adept at handling complex product categories like electric vehicle batteries and advanced textiles present superior growth arbitrage opportunities.
Conclusion and key strategic takeaways
The Product Take-Back Program Market represents an essential pillar of corporate sustainability. Reaching 98.51 Billion by 2033 requires seamless integration of retail, manufacturer, and third-party reverse logistics networks to capture maximum residual value.
Research methodology for baseline estimates
Our methodology triangulates trade registry data, primary stakeholder interviews with waste management executives, and secondary macroeconomic indicators. Baseline figures for 2026 are cross-verified against corporate ESG disclosures and customs statistics.
Scope of the report and coverage parameters
This report covers global market dynamics for take-back programs from 2026 through 2033. Limitations include restricted data transparency in informal recycling sectors across developing economies, focusing primarily on formal enterprise and municipal programs.
Recent developments, partnerships, and strategic moves
Recent milestones feature major logistics partnerships between retailers and Vestas Wind Systems AS or Staples Inc. to streamline commercial returns. Firms are aggressively deploying proprietary trade-in software to capture secondary market share.